The ACA Marketplace: Open Enrollment, Subsidies and Special Enrollment Periods
Open enrollment runs November 1 to January 15. How marketplace subsidies work since the enhanced credits have expired — including the return of the 400% cliff.
For anyone in the United States who does not get health coverage through an employer, through Medicare or through Medicaid, the individual marketplace created by the Affordable Care Act is usually where coverage comes from. Two things about it decide whether you can enroll and how much you pay: the calendar and your income relative to the federal poverty level.
The calendar comes first
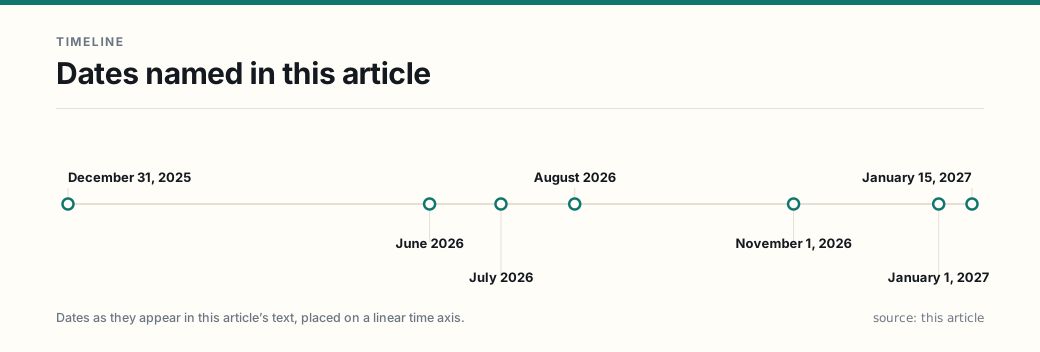
The marketplace has an annual Open Enrollment Period. On the federal exchange (HealthCare.gov) it runs from November 1 to January 15. For coverage starting January 1, 2027 the window opens November 1, 2026 and closes January 15, 2027 — enroll by December 15 for a January 1 start.
That end date was briefly in doubt. The 2025 Marketplace Integrity rule would have closed the federal window in mid-December from the 2027 plan year onward, but a federal court vacated that provision in June 2026, and CMS confirmed in early August 2026 that HealthCare.gov states keep the traditional November 1 – January 15 calendar. HHS has appealed, so the 2028 season is not settled — the 2027 dates are. State-run marketplaces set their own end dates, and several use different ones.
Outside that window you cannot simply sign up, regardless of how much you want coverage. The exception is a Special Enrollment Period, triggered by a qualifying life event — and it usually lasts 60 days, counted from the event.
Qualifying events include:
- Losing other coverage, such as leaving a job or aging off a parent’s plan
- Marriage, divorce or the birth or adoption of a child
- Moving to a new area where different plans are offered
- A change in household income that affects eligibility for subsidies
- Losing Medicaid or Children’s Health Insurance Program eligibility
- Certain changes in immigration status
Losing coverage is the big one, and timing is unforgiving. If you lose employer coverage on the 30th, the 60-day clock starts then. Enroll late and you may face a gap with no coverage at all, because a special enrollment period does not reopen once it closes.
How the subsidy actually works
Two separate forms of help exist, and people routinely confuse them.
The premium tax credit reduces what you pay monthly. It is calculated from your estimated household income for the year relative to the federal poverty level for your household size, and it caps what you pay for a benchmark plan at a percentage of that income — up to 400% of the federal poverty level, and no further. You can take it in advance as lower monthly premiums, or claim it when you file your tax return — or a mix of both.
The important consequence: it is reconciled against your actual income. If you took the credit in advance based on an estimate of $55,000 and actually earned $75,000, you may owe part of it back when you file. If you earned less, you may get more. Reporting income changes to the marketplace during the year is not optional housekeeping; it is how you avoid a surprise in April.
Cost-sharing reductions are different. They reduce the deductible, copays and out-of-pocket maximum, but only for people who qualify by income and who enroll in a Silver-tier plan. This is the single most valuable and most missed piece of the marketplace: for people in that income range, choosing a Bronze plan instead of Silver can cost far more than the premium difference suggests, because the cost-sharing help is tied to Silver.
What changed for 2026: the subsidy cliff is back
The credit itself never went away, but the temporary enhancement to it did, and the difference is large enough to change what you will pay.
The American Rescue Plan Act of 2021 removed the income ceiling and capped premium contributions at 8.5% of income, and the Inflation Reduction Act extended that through 2025. It expired on December 31, 2025. For the 2026 plan year the pre-2021 structure applies again:
- The credit ends at 400% of the federal poverty level. At 400% a household still receives help; one dollar above it, the credit is $0. That vertical drop, with no phase-out, is the “subsidy cliff.” For a household of four in the contiguous states the line falls at about $132,000 of income for 2027 coverage, using the 2026 poverty guidelines that govern that year.
- Required contributions rose at every income level. For a single person, the share of income you are expected to put toward a benchmark plan climbs from 2.15% at the bottom of the range to 10.22% at 400% FPL — set by IRS Revenue Procedure 2026-26 — instead of being capped at 8.5% for everyone.
- Cost-sharing reductions survived. They remain available on Silver plans from 100% to 250% FPL, which is why the Silver advice below still holds. For 2027 the reduced out-of-pocket maximum is $4,000 at 100–200% FPL and $9,600 at 200–250% FPL, against the standard ceiling of $12,000 for self-only coverage.
Two consequences are worth planning around. First, income near the line now matters more than it has since 2020 — a raise, a bonus, a capital gain or a Roth conversion can move a household across it, and the swing is measured in thousands of dollars a year, not hundreds. Second, the credit is still reconciled against what you actually earn: take it in advance, earn more than you estimated, and you repay the difference on Form 8962 when you file — in full, if your income lands above 400% FPL, because the repayment limits that soften the blow for lower earners do not apply once you are past the cliff.
Above 400% FPL you are not locked out of coverage: you can still buy any marketplace plan, you simply pay full price. A household whose cheapest available plan would cost more than the affordability threshold — 10.22% of income for 2027 — may qualify for an affordability exemption that allows buying a lower-cost Catastrophic plan. Be careful not to confuse that with the separate income-based hardship expansion, which would have opened Catastrophic plans to anyone earning above 250% or below 100% of the poverty level; a federal court stayed that route in July 2026, so it does not apply for 2027. The full picture is in The 2027 Marketplace runs on a court-modified rule.
Three details that catch people out:
- Do not price the plan against the wrong year’s poverty line. Eligibility is measured against the poverty guidelines in effect when the coverage year’s open enrollment began — for 2027 coverage, the guidelines in effect on November 1, 2026. Estimating against a later figure moves your percentage of FPL and can flip you across the 400% line.
- The out-of-pocket maximum is not the same as the deductible. The ceiling is the most you pay for in-network essential health benefits in a plan year; the deductible is what you pay before the plan shares costs at all. A plan can have a modest ceiling and a very large deductible.
- Silver is not a quality tier. It is an actuarial value band, and for anyone at 100–250% FPL it is the only tier where the cost-sharing reductions attach. Choosing Bronze to save premium forfeits that help entirely.
Where Medicaid fits
In states that expanded Medicaid under the ACA, adults below a set income threshold generally qualify for Medicaid rather than a marketplace plan, and applying through the marketplace routes you there automatically. In states that did not expand, adults below the poverty line can fall into a coverage gap: too much income for the state’s narrow Medicaid rules, too little to qualify for marketplace subsidies. Which state you live in therefore changes your options materially.
What is not compliant coverage
Short-term limited-duration plans are sold as cheap alternatives. They are not required to cover the essential health benefits, they can exclude pre-existing conditions, they can cap annual payouts, they can refuse renewal, and they do not satisfy the individual coverage requirement in states that have one. They are genuinely cheaper for a reason, and the reason is that they cover less.
The same caution applies to health sharing ministries, which are not insurance and are not regulated as insurance.
The scam that follows every subsidy season
No one can sell you eligibility. Enrollment help is free, and every legitimate route to a Marketplace plan ends at HealthCare.gov or your state’s exchange. Treat these as fraud, not sales:
- Anyone charging a fee to “unlock” or “release” a subsidy. The premium tax credit is computed by the Marketplace from the income you report. There is nothing to release and no fee to pay.
- Cold calls or texts offering a “special subsidy” or “Obamacare stimulus card.” Real Marketplace contact follows your own application or a request you made, and it does not arrive from a number you have never dealt with.
- Sites that look like HealthCare.gov but do not end in .gov. Payment information typed into a look-alike domain goes to whoever registered it.
- Requests for your Login.gov password or a one-time code by phone. No agency asks for either.
If a message pushes you to act now because the money is about to expire, that urgency is the tell.
How to enroll
- Start at HealthCare.gov if your state uses the federal platform, or your state’s own marketplace if it runs one. Beware of third-party sites that charge for a service the marketplace provides free.
- Enter household size, income and everyone who needs coverage. The site returns plans with the subsidy already applied, so you see the real monthly price.
- Compare plans using the out-of-pocket maximum first, then check that your doctors and prescriptions are covered.
- If your income is in the range that qualifies for cost-sharing reductions, enroll in a Silver plan to capture them.
- Report any income change during the year, and reconcile everything on your tax return.
The system rewards people who look at it once a year with a calculator rather than once when something goes wrong. Open Enrollment is the moment to do that — and the window closes faster than it looks, particularly in a year when subsidy eligibility is worth checking twice. The 2027 income lines, the published contribution percentages and the four checks worth running before November 1 are set out in The ACA Subsidy Cliff Is Back.
One more check before the window opens: in August 2026 CMS canceled roughly 315,000 Marketplace policies it confirmed were enrolled without the owner’s consent, and it plans further verification of hundreds of thousands more. Log in, confirm the plan, agent of record and application details are yours, and know what to do if they are not — the steps are in What to Check After the Marketplace Fraud Cancellations.
Sources
Each source is a primary or official reference, checked before publication. Links open the original.
- HealthCare.gov — enrollment dates, eligibility and the premium tax credit
- Centers for Medicare & Medicaid Services — premium adjustment percentage and maximum annual limitation on cost sharing for the 2027 benefit year ($12,000 self-only / $24,000 family), January 29, 2026
- IRS Revenue Procedure 2026-26 — applicable percentages for plan years beginning in 2027
- HHS, 'Annual Update of the HHS Poverty Guidelines,' 91 Fed. Reg. 1797 (January 15, 2026) — the 2026 guidelines governing 2027 coverage
- Congressional Research Service R48290 — enhanced premium tax credit and 2026 exchange premiums
- Internal Revenue Service — Premium Tax Credit and Form 8962 reporting requirements
- Login.gov — the account system used to sign in to federal benefits applications
- City of Columbus et al. v. Kennedy, No. 1:26-cv-02215 (D. Md.), order entered July 16, 2026 — the stay of the 2027 payment rule's income-based Catastrophic-plan hardship expansion, which is why the affordability test (not income alone) governs for 2027; IRS Revenue Procedure 2026-26 for the 10.22% affordability threshold